Published September 24, 2026
Debunking the 20% Myth: What Buyers Actually Need for a Down Payment (and the Hidden Costs to Budget For)
Debunking the 20% Myth: What Buyers Actually Need for a Down Payment (and the Hidden Costs to Budget For)
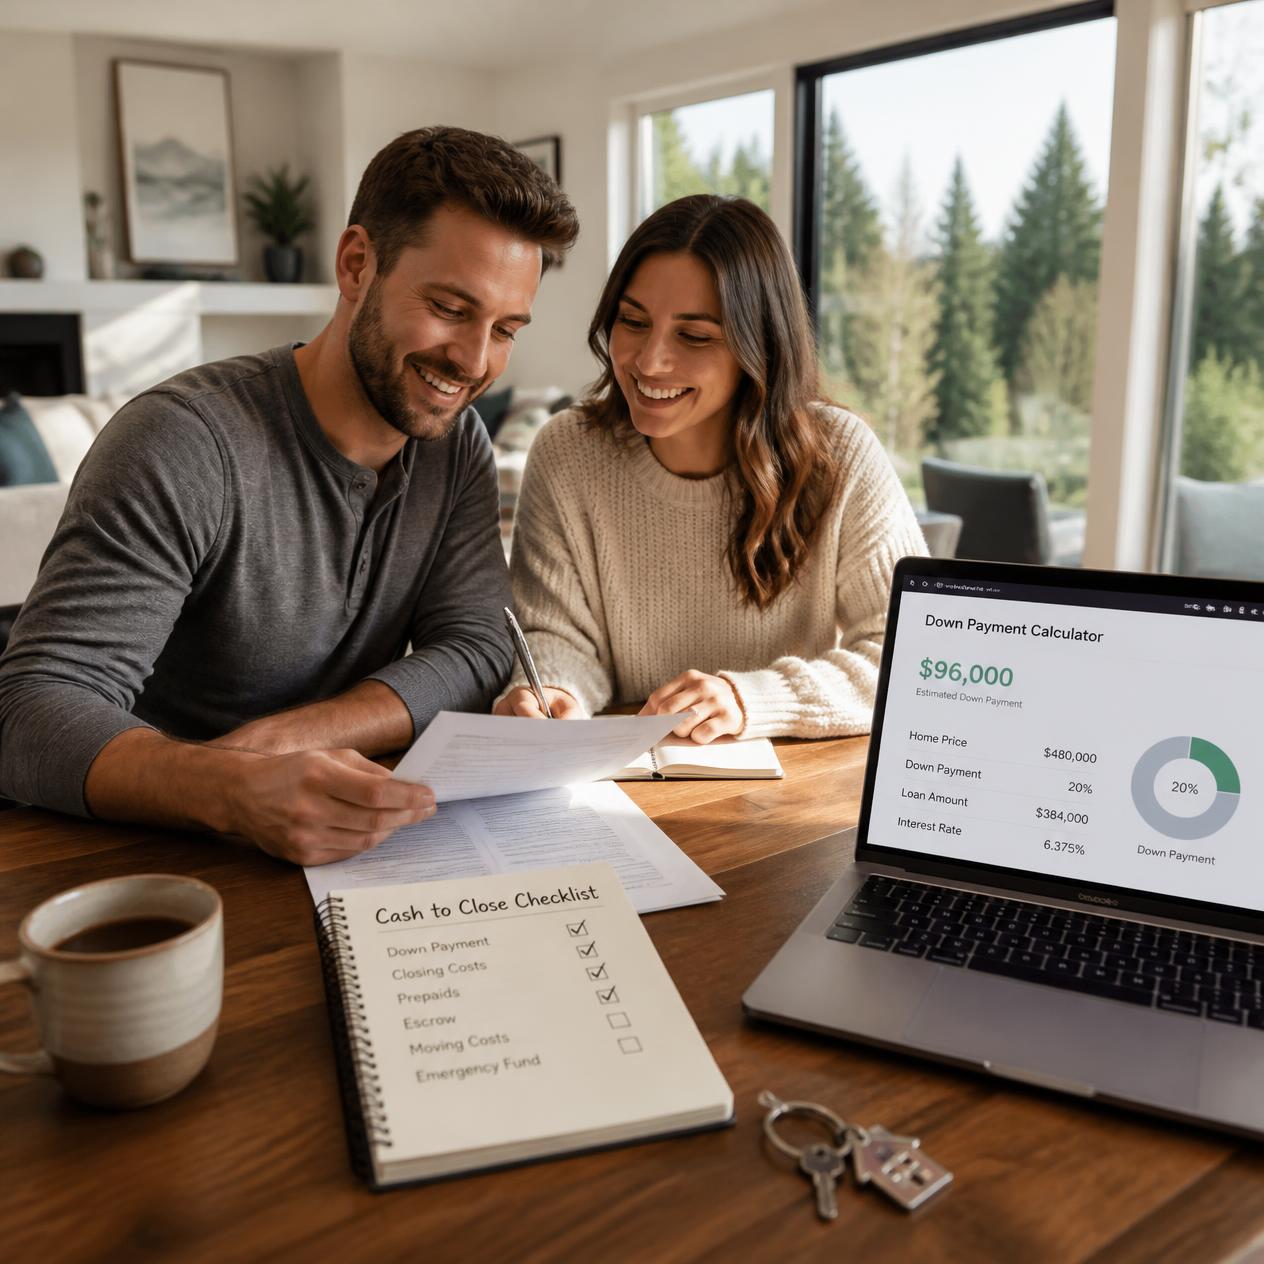
One of the single biggest misconceptions holding prospective buyers back today is the belief that you must save a 20% down payment to purchase a home.In reality, waiting until you have 20% liquid cash sitting in a bank account can add years of renting to your timeline—years during which home prices and interest rates may continue to shift.
To help you build a realistic cash-to-close strategy, here is a breakdown of what you actually need for a down payment, along with the "hidden" out-of-pocket costs every buyer needs to prepare for before closing day.
1. The True Down Payment Minimums
While putting 20% down eliminates the need for Private Mortgage Insurance (PMI), it is far from mandatory. Depending on the loan program, down payment minimums are significantly lower:- Conventional Loans: First-time buyers can often qualify with as little as 3% down.
- FHA Loans: Backed by the Federal Housing Administration, these require a 3.5% minimum down payment and allow for lower credit score thresholds.
- VA and USDA Loans: Qualifying military veterans, active duty service members, and buyers in designated rural areas can secure a mortgage with 0% down.
What Does This Look Like in Real Dollars?
On a $500,000 home, the difference in initial cash required is significant:- 20% Down Payment: $100,000
- 5% Down Payment: $25,000
- 3.5% Down Payment (FHA): $17,500
- 3% Down Payment (Conventional): $15,000
2. Closing Costs: The 2%–5% Rule
Your down payment is only one portion of the total cash required at closing. Buyers must also cover closing costs, which are third-party administrative, legal, and lender fees necessary to process and finalize the loan. Buyers are often able to negotiate receiving extra funds from the seller towards closing costs to reduce the immediate cash need.Across most markets, buyer closing costs generally average 2% to 5% of the total purchase price (or roughly 2.8% to 3% as a solid working average). On a $500,000 home, expect to set aside an additional $10,000 to $25,000.
What Is Included in Closing Costs?
- Lender Fees: Loan origination, underwriting, processing, and credit report pulls (typically 0.5%–1% of the loan amount).
- Title & Escrow Services: Title search, title insurance policies (protecting against ownership disputes), and escrow closing fees.
- Appraisal & Inspection: Third-party appraisal to verify property value ($500–$800) and general home inspection fees ($400–$700).
- Prepaids & Escrow Reserves: Advanced payments set aside to establish your escrow account for upcoming property taxes and homeowners insurance.
3. The Ongoing "Hidden" Monthly Costs
Beyond the one-time cash required at closing, buyers must account for recurring recurring housing expenses that extend past the base principal and interest loan payment.Total Monthly Payment = Principal + Interest + Property Taxes + Home Insurance + (HOA / PMI)
Property Taxes
Property taxes vary by county and state, but typically range from 1% to 2% of the home's assessed value annually. On a $500,000 home, a 1.25% property tax rate adds approximately $520 per month to your housing payment.Homeowners Insurance
Insurance premiums have shifted upward nationally due to extreme weather patterns and rising construction labor costs. Always get an insurance quote early in the contract period, as premiums can range anywhere from $1,000 to $2,500+ annually depending on property location, age, and roof condition.HOA Fees (Homeowners Association)
If you are purchasing a condominium, townhouse, or home in a planned community, account for monthly or annual HOA dues.- Scope: Dues can range from $50/month to over $500+/month.
- Budget Impact: HOA fees directly impact your mortgage qualification ratio, as lenders count the full HOA fee as part of your monthly debt obligations.
Private Mortgage Insurance (PMI)
If you put down less than 20% on a conventional loan, you will pay monthly PMI until you reach 20% equity in the home. PMI typically costs 0.5% to 1.5% of your total loan balance per year (roughly $150–$300/month on a typical purchase), but it can be removed once your property value rises or your principal balance drops sufficiently.Summary Checklist: Your Total Cash Needed to Buy
To avoid surprises, structure your savings goal using this simple formula:- Down Payment: 3% to 20% of the target purchase price.
- Closing Costs: ~3% of the target purchase price.
- Maintenance Reserve: 1% of the home’s purchase price set aside in a high-yield liquid account for unexpected repairs after move-in.
Noah Kragerud
Team Lead | Ark Realty Group | Keller Williams Sunset Corridor
or another way