Published October 22, 2026
Overcoming the "Lock-In Effect": How to Right-Size Your Life Without Destroying Your Monthly Budget
Overcoming the "Lock-In Effect": How to Right-Size Your Life Without Destroying Your Monthly Budget
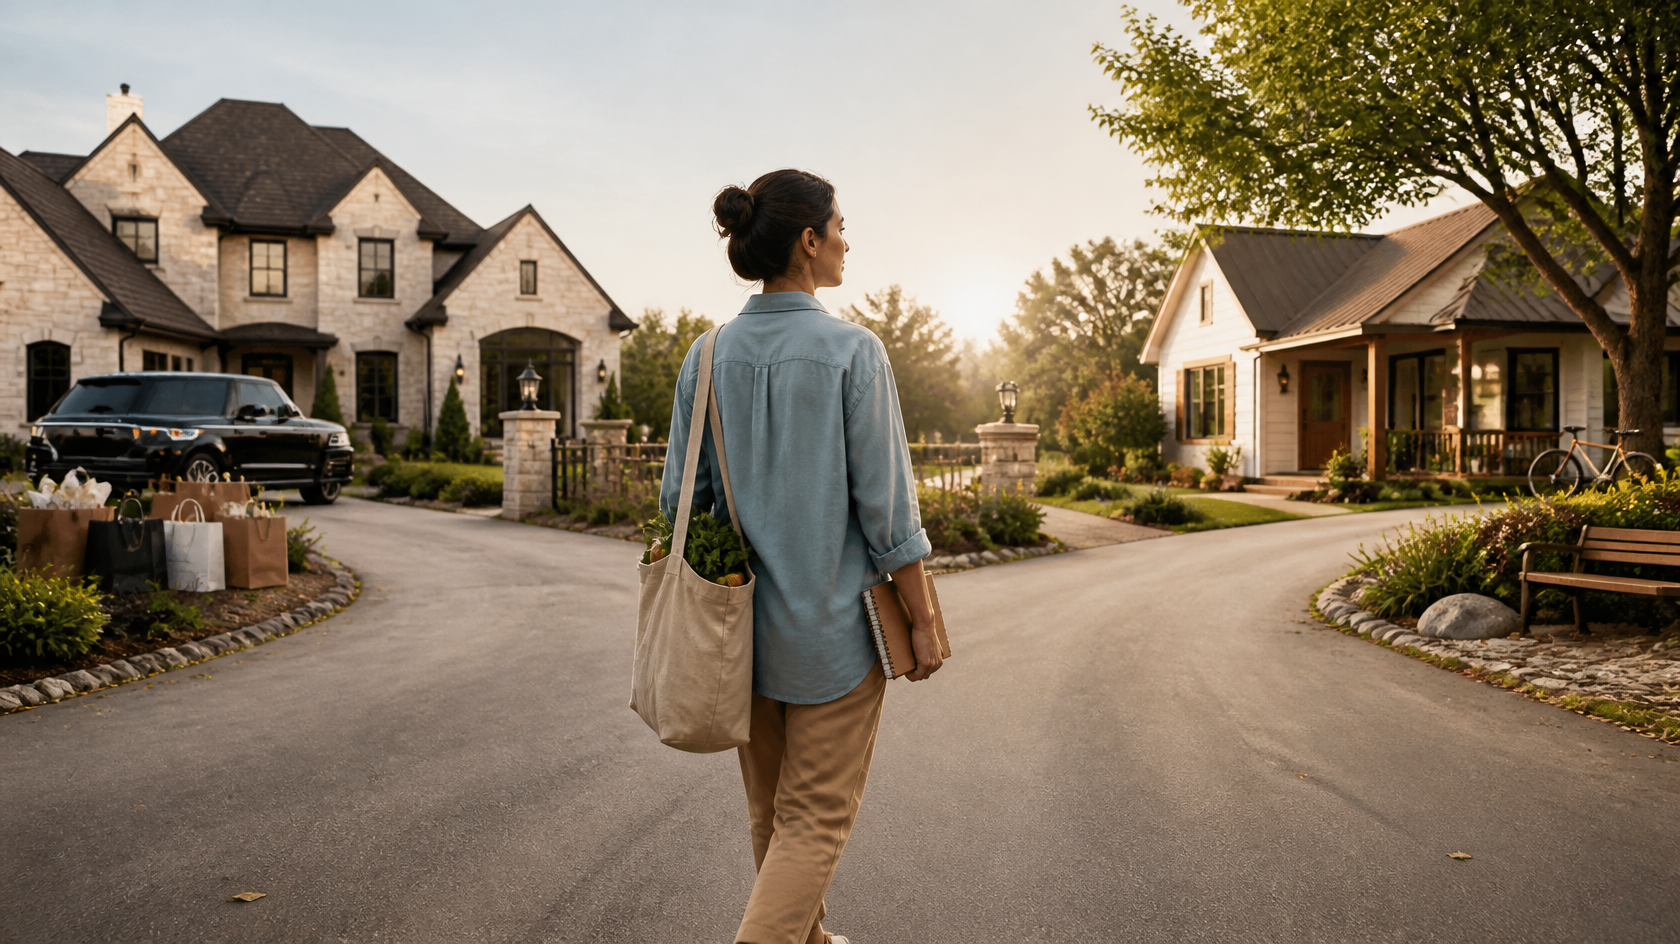
If you’re currently sitting on a 3% or 4% fixed-rate mortgage, the thought of trading it in for today’s 6.5% interest rates can feel like a non-starter. You might need a bigger home for a growing family, a downsized layout for retirement, or a change of scenery closer to work—yet the fear of doubling your interest rate keeps you stuck in place.
You aren’t alone. This financial dilemma is known as the "Lock-In Effect," and it has left millions of homeowners feeling trapped in homes that no longer fit their lives.
However, holding onto a low rate at the cost of your daily lifestyle and long-term comfort doesn't have to be your only option. By using smart financial moves and leverage strategies, you can transition into your next home without taking an unbearable hit to your monthly budget.
Here is how you can break free from the rate lock and make your next move work.
1. Leverage Your Built-Up Equity to Lower Your New Principal
While interest rates have risen over the last few years, home values have also climbed significantly. If you’ve owned your home for more than a few years, you are likely sitting on a substantial amount of home equity.
Instead of rolling all your profits into savings, applying a substantial portion toward the down payment on your next home significantly reduces your total loan amount. A higher interest rate on a significantly smaller mortgage balance often results in a manageable monthly payment that looks much closer to what you’re paying today.
The Math in Action: A 6.5% interest rate on a $300,000 balance carries a lower monthly principal and interest payment than a 3.5% rate on a $600,000 balance. Focus on the total dollars borrowed, not just the percentage rate.
2. Use Seller Concessions to Buy Down Your Rate
In today's more balanced housing market, buyers have significantly more negotiating power than they did during the frantic bidding wars of past years. One of the most effective tools to mitigate higher rates is asking the seller for rate buydown concessions.
- Temporary Buydowns (e.g., 2-1 Buydown): The seller pays upfront funds to reduce your interest rate by 2% in year one and 1% in year two, giving you a lower initial payment while you settle in.
- Permanent Rate Buydowns: You can negotiate for the seller to pay "discount points" at closing, which permanently lowers your interest rate for the full 30-year term of the loan.
When buying your next home, strategic negotiations can bring a 6.5% market rate down into the 5s—easing the transition from your current ultra-low rate.
3. Explore Recasting or Porting Options
Before assuming a standard 30-year fixed loan is your only route, consult with a trusted lender about alternative mortgage structures:
- Mortgage Recasting: If you buy your next home before selling your current one, a recast allows you to make a large lump-sum payment from your eventual home sale toward your new mortgage principal. The lender then recalculates your monthly payment based on the lower balance without forcing you to refinance or pay heavy origination fees.
- Assumable Mortgages: If you are purchasing a home with an existing FHA, VA, or USDA loan, you may be eligible to assume the seller's lower rate and low-interest loan balance directly.
4. Evaluate the True Cost of Staying Put
When deciding whether to stay or sell, it is easy to focus strictly on mortgage math while overlooking the hidden costs of remaining in a home that no longer fits your needs:
- Remodeling Costs: Attempting to alter or expand your current home to fit your lifestyle can easily cost tens of thousands of dollars in cash out-of-pocket, which carries its own financial trade-offs.
- Quality of Life: Long commutes, inadequate space, high maintenance on a home that is too large, or multi-story layouts that no longer suit your mobility all carry an invisible cost to your day-to-day well-being.
The Bottom Line
A low mortgage rate is a great asset, but it shouldn't be a golden cage. Your home should serve your life—not the other way around.
By combining your current home equity with tactical financing strategies like seller-funded rate buydowns and recasting, you can right-size your living situation while keeping your monthly budget well within reach.
Noah Kragerud
Team Lead | Ark Realty Group | Keller Williams Sunset Corridor
or another way